
Goldman Sachs moves into third phase of AI adoption
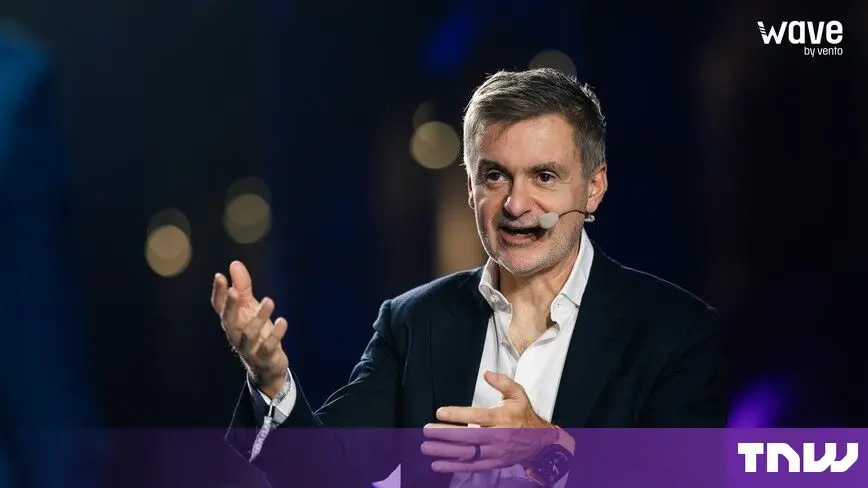
Goldman Sachs is entering a third phase of artificial intelligence adoption, one in which the central question shifts from cost savings to revenue generation, according to the bank's chief information officer, Marco Argenti. Speaking at a technology conference in Turin, Argenti framed the transition as a change in mindset rather than a simple upgrade in tools. The session, titled 'Mindset, not skillset', explored how AI is reshaping work inside one of the world's largest financial institutions.
'How do you make money because of AI, not only how do you save money because of AI?' Argenti asked. That question now sits at the center of Goldman's AI strategy. The bank has moved beyond experiments and productivity pilots. It is now looking for ways to use AI to win business, serve clients better, and create new sources of value.
Argenti joined Goldman in 2019 from Amazon Web Services, where he was vice president of technology. His background in cloud computing and large-scale enterprise platforms has informed his approach to AI adoption. He said AI now touches pretty much everyone at Goldman. The working day used to start with the first email. Now it may start with a question to the bank's internal assistant, or with an agent that has already begun a task.
Three waves of adoption
Argenti described the bank's AI journey as three overlapping waves. The first wave was made up of people who like to try new things. Developers led the way, more than 12,000 of Goldman's roughly 47,000 staff. For those employees, working with AI is already the norm. They use it to write code, debug systems, generate tests, and explore design options. The tool has become part of the daily workflow rather than a special project.
The second wave rethinks the bank's processes. That means questioning every step of a workflow and asking whether it should exist at all, rather than doing the same thing faster. Argenti said the aim is what traders call straight-through processing: large processes that run end to end with no human step. In banking, many workflows still depend on handoffs, approvals, and manual checks. AI agents can potentially handle entire sequences, from data collection to decision support to execution, if the right controls are in place.
The third wave, which Argenti said is 'emerging right now', is about growth. It uses AI not only to make the company more efficient but also to help it grow. That could mean faster product development, better client coverage, more personalized services, or new analytical capabilities. The shift matters because most early enterprise AI deployments focused on cost reduction. The next phase will test whether AI can drive top-line results.
Measuring the return on AI
Goldman used to measure AI through proxies, such as how often developers committed code. Argenti said nobody could trace those metrics to dollars. In the last six months or so, outcomes have changed. Teams finish a three-month project in two months. Projects that fell below the line in zero-based budgeting now fund themselves. That is a significant shift. It means AI is no longer just a productivity curiosity. It is beginning to show up in project economics, resource allocation, and budget decisions.
Asked whether that means fewer people, Argenti said the bank might have that option. But every engineering backlog holds far more work than gets funded in each planning cycle. As long as there is appetite to grow, there will be plenty of work first. That answer reflects a broader tension in enterprise AI. Automation can reduce the need for some roles, but it can also unlock demand for new products, services, and internal capabilities. The net effect on employment depends on how companies choose to redeploy talent and where they see growth opportunities.
For banks, measuring AI return is not straightforward. Financial institutions operate under strict regulatory scrutiny. They must document decisions, protect customer data, and manage model risk. A productivity gain in software development may be easy to see, but a revenue gain from AI-driven advice or trading is harder to attribute. Goldman's approach suggests a move toward concrete project-level metrics: cycle time, throughput, cost per transaction, client acquisition, and risk-adjusted returns. The bank is trying to connect AI use to the P&L, not just to activity metrics.
The developer becomes a manager of managers
The developer's job is changing, Argenti said. Developers now explain what needs doing, delegate it to AI agents, and supervise their work. Agents can now create their own sub-agents, so a developer becomes a manager of managers. The job is to describe clearly what a good outcome looks like, and to manage resources and priorities, almost like an entrepreneur.
That shift has implications for hiring, training, and organizational design. If developers spend less time writing every line of code, they need stronger skills in problem definition, system design, review, and judgment. They also need to understand how to orchestrate multiple agents, set constraints, and verify results. The 'mindset, not skillset' theme captures this: the most valuable capability may be the ability to adapt, ask better questions, and manage autonomous systems rather than master a single tool.
Another chief executive at the same event argued that companies must redesign work around AI. That view is increasingly common among technology leaders. Adding AI to existing processes often produces limited gains. Redesigning processes around AI agents can produce larger gains, but it requires rethinking roles, handoffs, and decision rights. In banking, that could mean fewer manual approvals, more real-time monitoring, and new kinds of human oversight.
Assume the model will make mistakes
At the heart of AI is a statistical machine that will not give the same result every time, Argenti said. So the bank assumes its models will make errors, like humans, and builds an environment that stops them doing harm. He compared it to a kindergarten: you remove the sharp edges instead of handing each child a safety policy. The analogy is vivid. Instead of relying on users to read long policy documents, the system should be designed so that dangerous actions are difficult or impossible.
That means securing where agents run and what they can access. It also means reading a model's chain of thought, and using other AI models to challenge its work. Goldman calls the approach zero trust and defence in depth. In practice, zero trust means no agent or user is trusted by default, even inside the corporate network. Defence in depth means multiple layers of controls: identity verification, least-privilege access, sandboxed execution, logging, monitoring, and human review for high-risk actions.
Financial institutions are also subject to model risk management rules. They must validate models, test them for bias and accuracy, and monitor them in production. Applying those disciplines to generative AI and agentic systems is new. It requires reading chain-of-thought reasoning, evaluating outputs, and using adversarial testing. The goal is not to eliminate errors. It is to contain them, detect them quickly, and prevent them from causing harm to clients, markets, or the bank itself.
Open-weight models and frontier systems
Choice is the most important currency, Argenti said. Open-weight models can be retrained on the bank's own knowledge, which helps with sovereignty and protecting its intellectual property. They are also cheaper for simple tasks. That combination is attractive for large enterprises. Open-weight models can be hosted internally, fine-tuned on proprietary data, and adapted to specific domains. They give the bank more control over where data resides and how models are used.
Frontier models have the strongest reasoning, he said, for problems nobody has solved before. He compared the choice to a truck and a Formula 1 car. The truck does the utility work. Where the business races, Goldman wants the most powerful car. The analogy captures a hybrid strategy. Not every task needs the most advanced model. Routine classification, summarization, and extraction can run on smaller, cheaper, open-weight models. Complex reasoning, research, and novel problem-solving may require frontier systems.
Another enterprise software executive at the same event said his company tests more than 100 models to pick the best one for each job. That approach is becoming standard. Enterprises are building model routers and evaluation frameworks that match tasks to models based on cost, latency, accuracy, and data sensitivity. This week, Mistral launched Large 4, an open-weight model, adding another option to a rapidly growing field. For banks, the choice is not ideological. It is operational. The right model depends on the task, the data, the risk, and the economics.
Goldman's dual approach reflects a broader reality in enterprise AI. Frontier models offer state-of-the-art reasoning, but they can be expensive and may raise data governance questions. Open-weight models offer control and cost advantages, but they require internal expertise to fine-tune, deploy, and maintain. Many companies will use both, routing simple tasks to open-weight models and complex tasks to frontier systems. The key is to build an architecture that allows switching as models improve and prices change.
What the third phase means for banking
Goldman's third phase is a signal for the wider financial industry. The first phase of AI adoption was about experimentation. The second was about process efficiency. The third is about growth. That progression is logical. Banks have large cost bases, complex workflows, and vast amounts of data. AI can reduce costs, but the bigger prize is revenue. AI can help banks serve more clients, personalize advice, accelerate research, detect fraud, and improve trading. It can also create new products and business models.
However, growth brings new risks. If AI systems make mistakes, they can harm clients and markets. If they are biased, they can lead to unfair outcomes. If they are opaque, they can be difficult to regulate. Goldman's emphasis on zero trust, defence in depth, and assuming errors suggests that governance is not an afterthought. It is part of the design. The bank's experience also shows that measuring ROI matters. Without clear metrics, AI programs can become endless pilots. With clear metrics, they can attract funding and scale.
Argenti's comments also highlight the changing nature of work. Developers are becoming managers of AI agents. Managers are becoming orchestrators of human and machine teams. The most important skill may be the ability to define outcomes, set priorities, and manage resources. That is an entrepreneurial mindset. As AI agents become more capable, the boundary between individual contributor and manager may blur. Organizations will need new career paths, training programs, and performance metrics.
For now, Goldman is focused on the third wave. It is asking how AI can help the bank make money, not just save money. It is measuring outcomes in project timelines and budget decisions. It is redesigning developer roles around agent supervision. It is building security that assumes models will fail. It is choosing between open-weight and frontier models based on the task. Those choices will shape how the bank competes in the years ahead. The truck and the Formula 1 car are both in the garage. The question is where to race.